Mortgage Lending Since 1996 Serving Utah & Idaho
Office · 435.627.9300 [email protected]
Krest Mortgage · Utah & Idaho

Lending, refined since 1996.

A trusted brokerage serving Utah and Idaho — every loan handled with the precision and care your home deserves.

Conventional · FHA · VA · USDA · Refinance
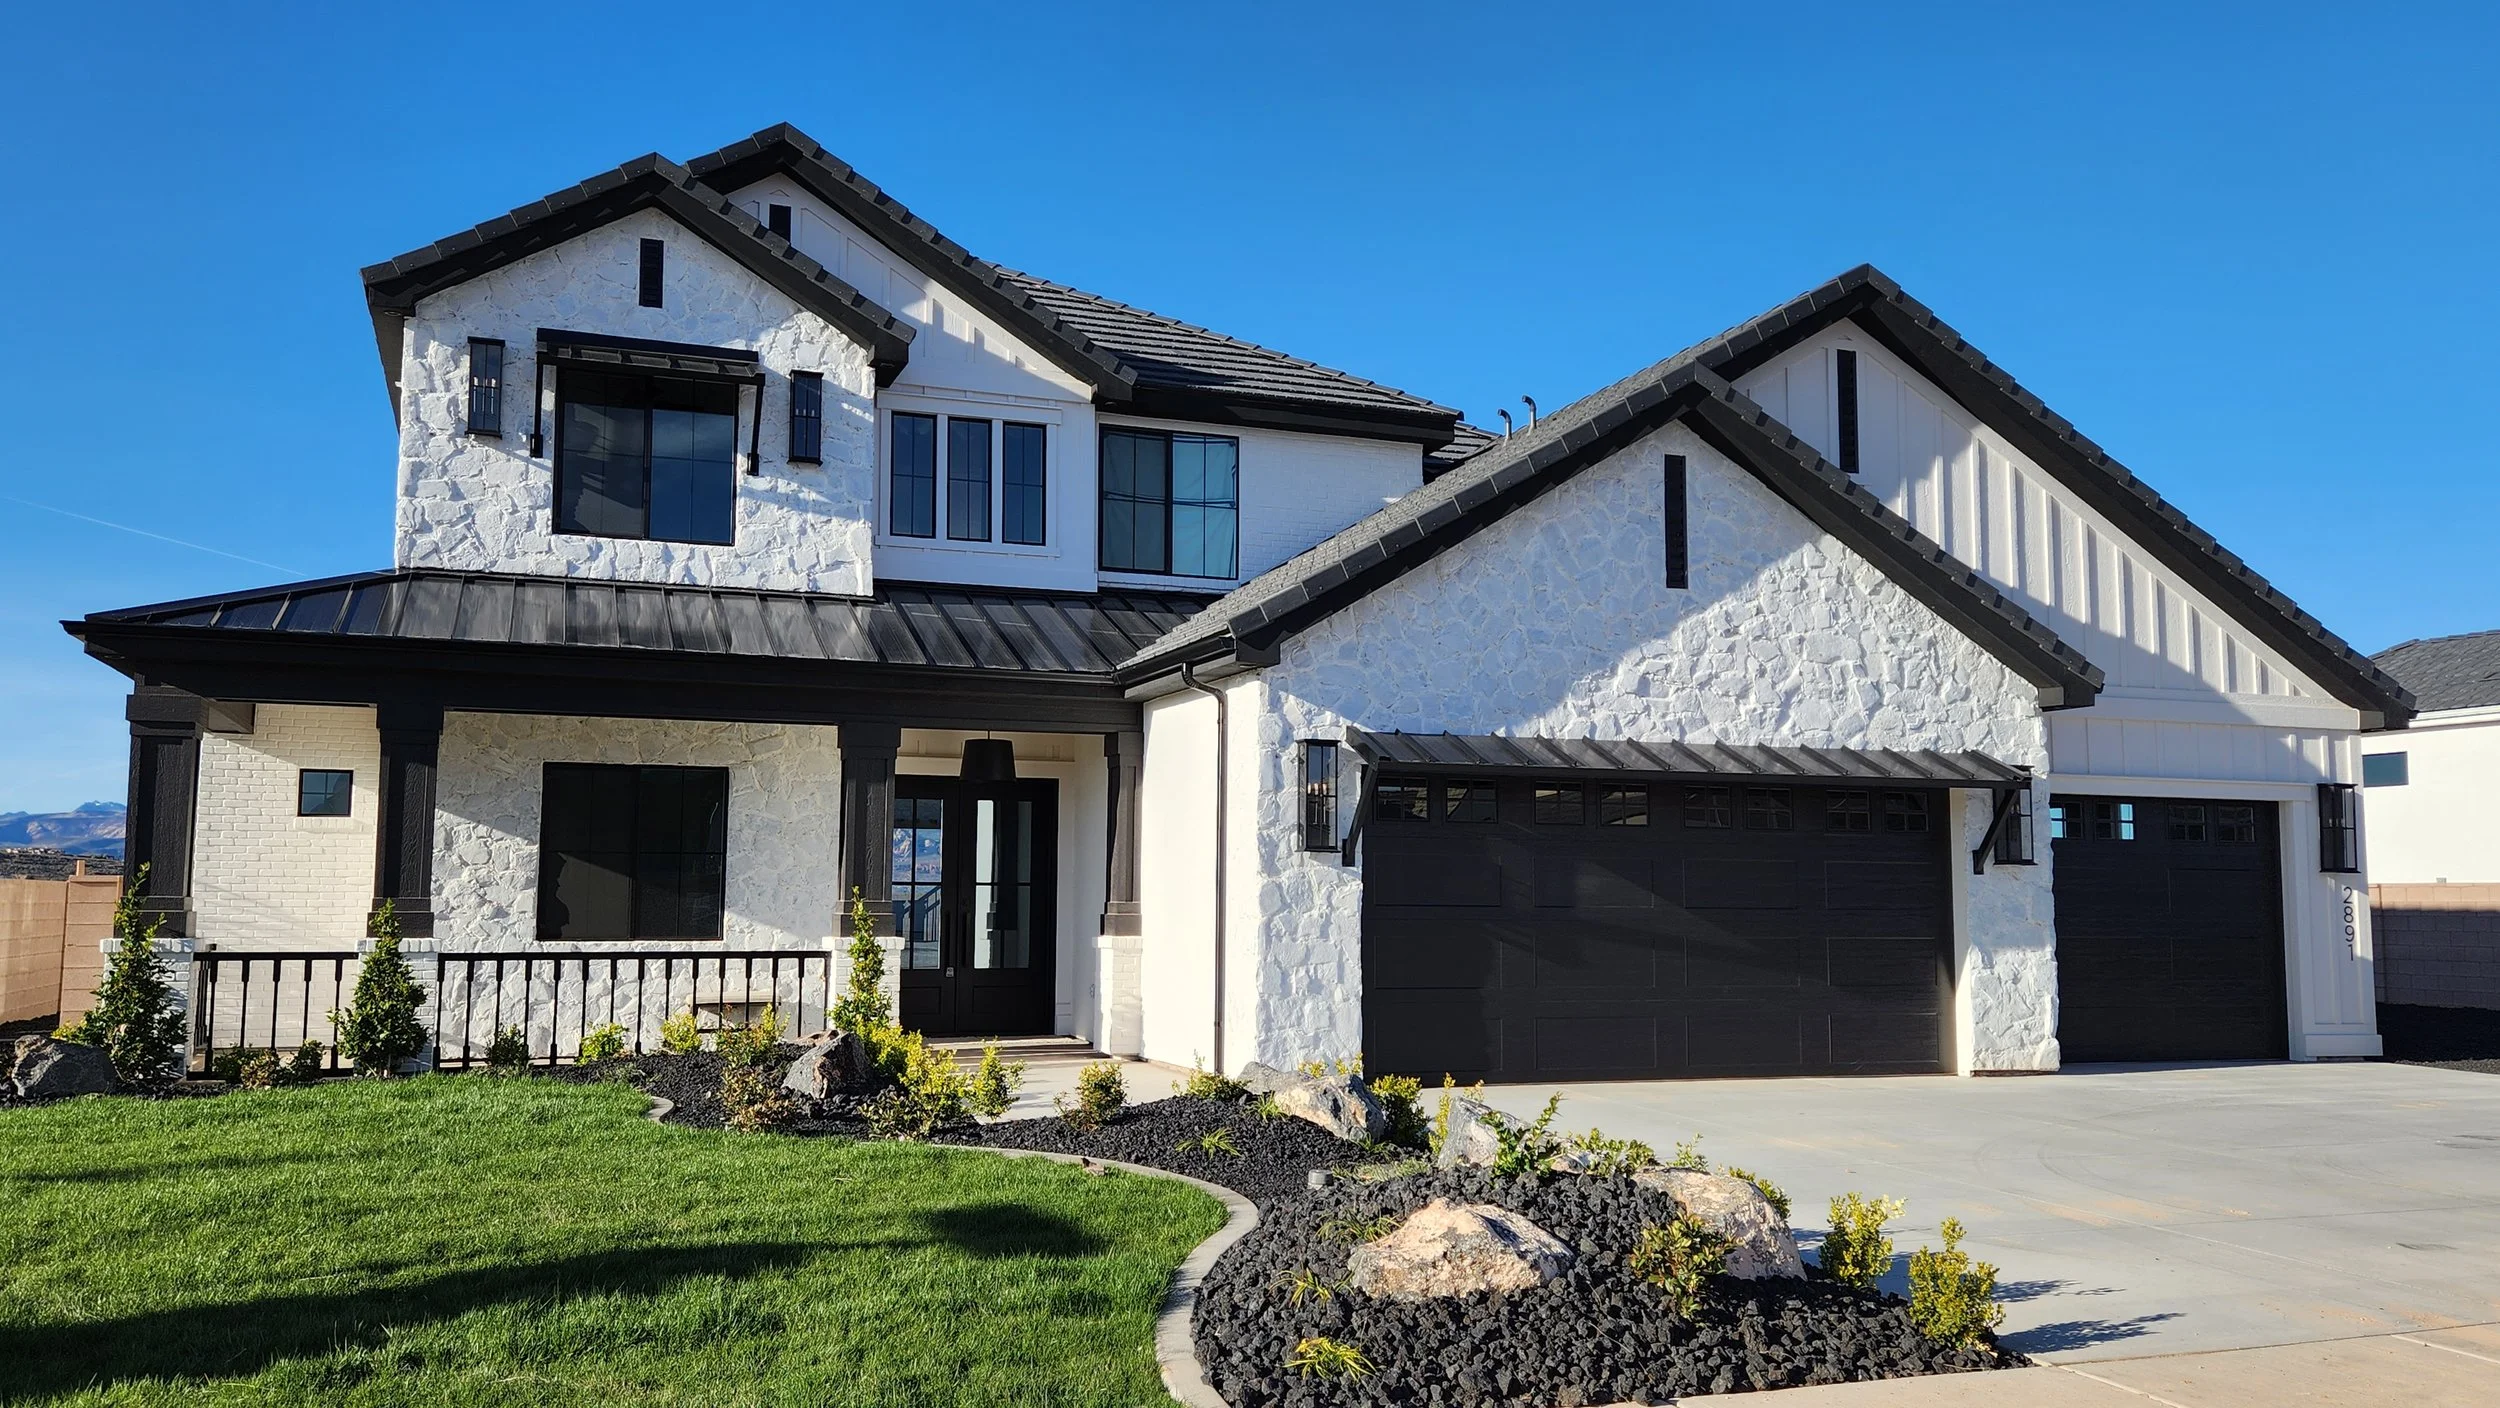
A handsome stone-and-board farmhouse with a sun-lit porch — the kind of home Krest helps clients into.
Established 2004 UT · ID
Krest Mortgage shield mark M · M · I · V
A House Built on Trust

Twenty-two years of steady hands, careful files, and clients who return.

Krest Mortgage was founded on a simple principle: a home loan is one of the most consequential signatures a family will ever make. We treat it that way. Every quote is built by hand, every file owned by a person who answers their own phone, and every closing earned through care — not volume.

1996
Lending Since
UT & ID
States Served
306273
Company NMLS
The Lending Library

Four mainstays, tailored to you.

Most clients arrive having heard the names but unsure of the differences. Here is a plain-spoken introduction to the loans we handle most — each one explained the way we would explain it across the desk.

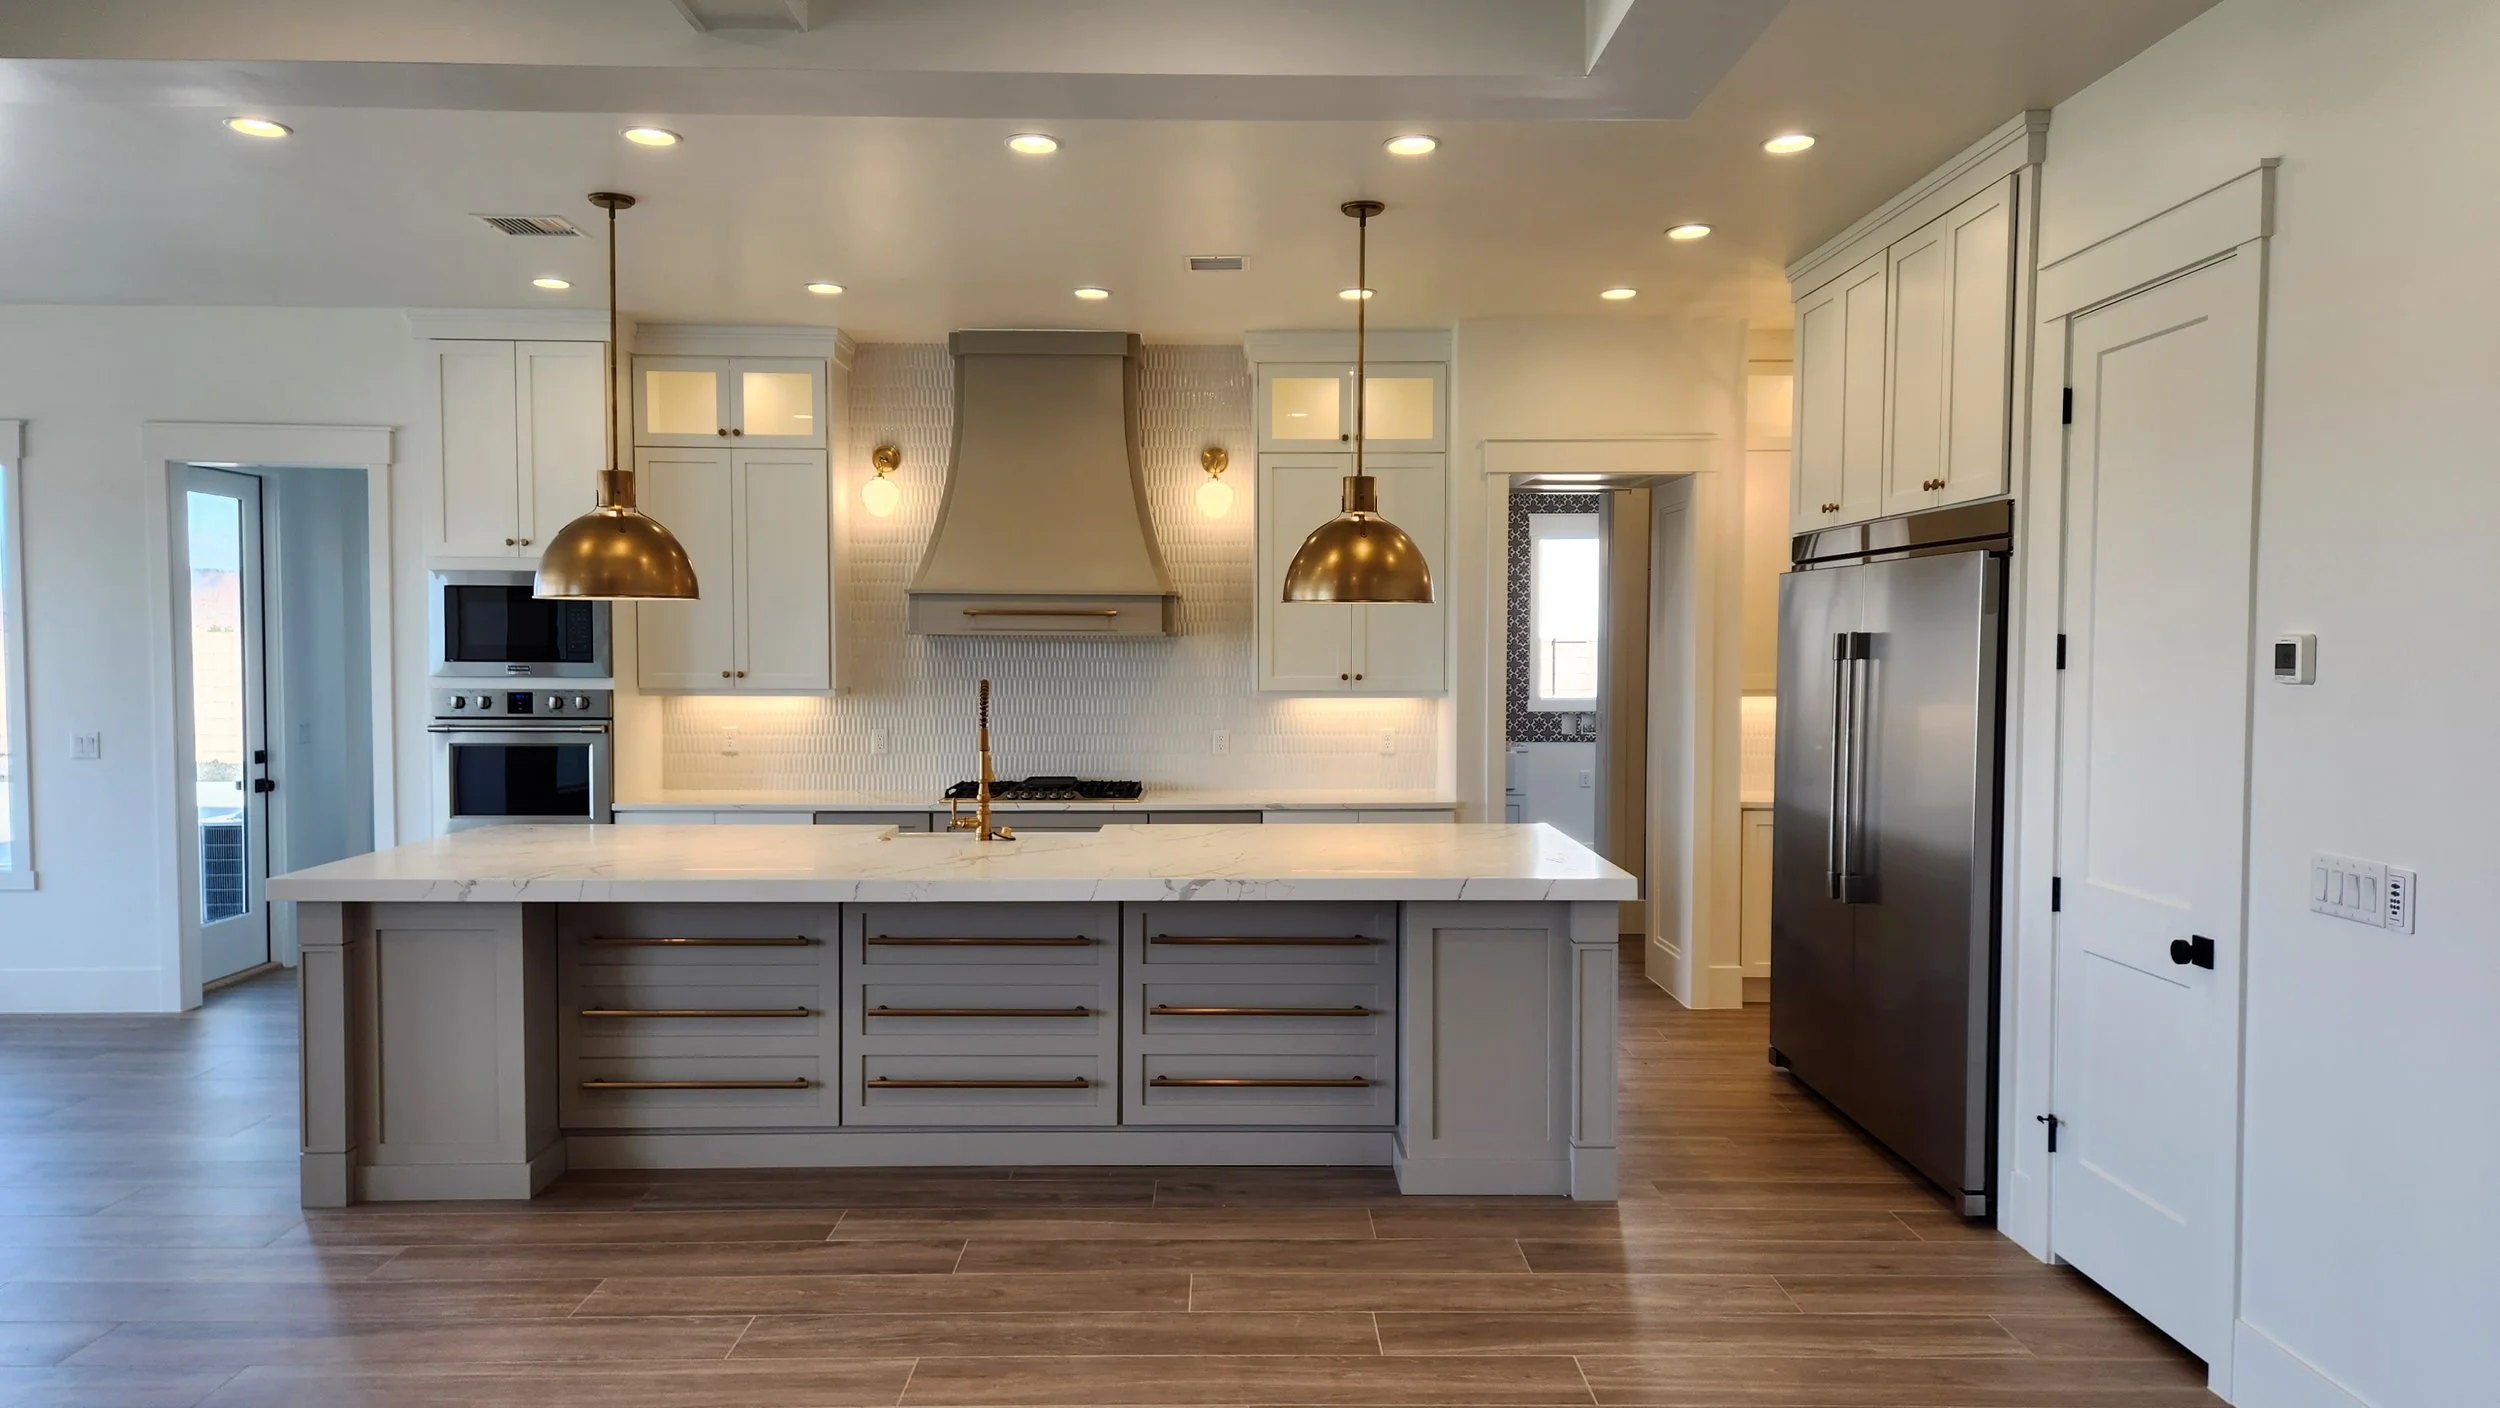
A handsome kitchen with a marble island and brass pendants — a conventional-loan home. I
I · Conventional

The classic thirty-year standard.

Backed by Fannie Mae or Freddie Mac, the conventional loan is the workhorse of American homebuying — and for good reason.

  • iAs little as 3% down for qualified first-time buyers; 5% down typical.
  • iiPrivate mortgage insurance falls off once you reach 80% loan-to-value.
  • iiiFixed and adjustable rates; terms from 10 to 30 years.
  • ivStrong choice for buyers with established credit (typically 620+).
Discuss a conventional loan →
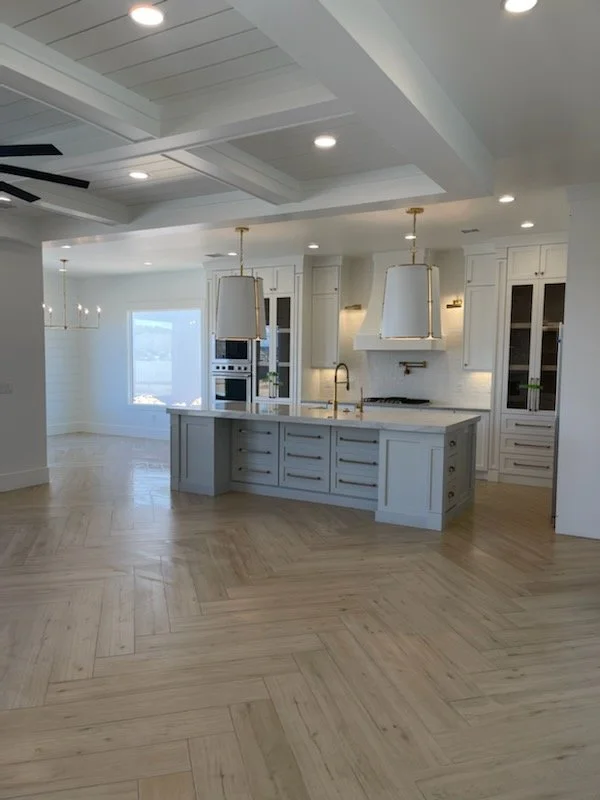
A bright open kitchen with herringbone floors — within reach with an FHA loan. II
II · FHA

The first key opens more doors.

Insured by the Federal Housing Administration, FHA loans were built for buyers who need a forgiving path into their first home.

  • iDown payments from 3.5% with a credit score of 580 or higher.
  • iiMore flexible underwriting on debt-to-income and credit history.
  • iiiGift funds and seller concessions are widely accepted.
  • ivOften the right answer for first-time buyers and growing households.
See if FHA fits →
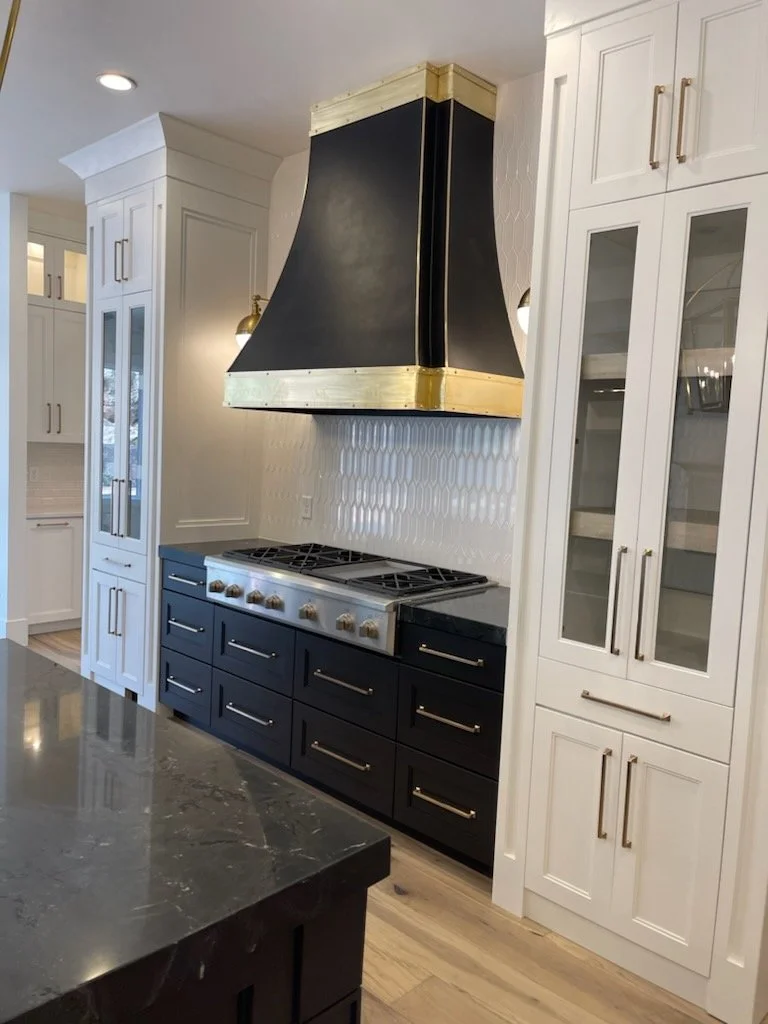
A refined kitchen with a black hood and brass trim — a VA-loan home for those who served. III
III · VA

For those who served, an honored rate.

Guaranteed by the Department of Veterans Affairs, the VA loan is one of the most generous loan programs in American lending. We are proud to handle them.

  • i0% down payment for eligible veterans, active duty & surviving spouses.
  • iiNo private mortgage insurance — ever.
  • iiiCompetitive, often below-market interest rates.
  • ivReusable benefit — your service earns this loan for life.
Use your VA benefit →
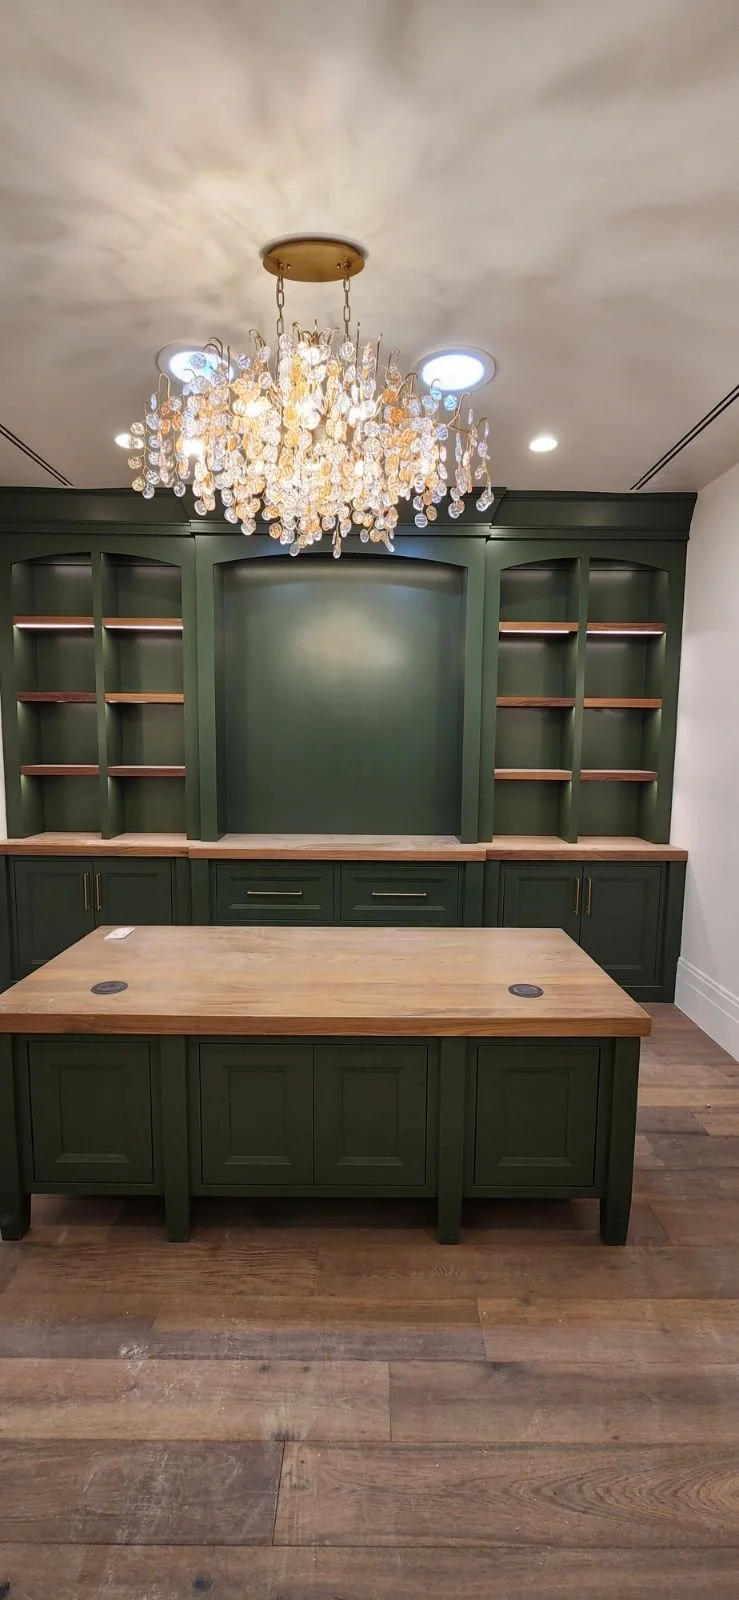
A green-cabinet study with a crystal chandelier — a home worth refinancing into. IV
IV · Refinance

Revisit the terms. Renew the loan.

A refinance is a quiet act of housekeeping — a chance to lower your rate, shorten your term, or put your equity to deliberate use.

  • iRate & term: a lower payment — in most cases, closing costs can be rolled into the new loan amount.
  • iiCash-out: equity converted to capital for renovation or debt.
  • iiiStreamline (FHA & VA): a lighter, faster path to a new rate.
  • ivWe'll review the numbers with you to confirm it makes financial sense, and go over the breakeven point.
Review my mortgage →
Beyond the Standard

For the non-traditional route.

Not every borrower's income, assets, or property fit a conventional file. These programs are reviewed individually to help determine whether they're a fit for qualifying buyers and homeowners looking to purchase or refinance.

Bank Statement

Bank Statement Loans

Qualify using personal or business bank deposits rather than tax returns — a common fit for self-employed borrowers and business owners.

P&L Statement

Profit & Loss Statement Loans

Qualify using a CPA- or tax-preparer-signed profit and loss statement, for self-employed borrowers whose tax returns don't tell the whole story.

Asset-Based

Asset Depletion Loans

Qualify using the strength of savings, investments, and retirement assets in place of traditional employment income.

Contract & Gig

1099 Loans

Qualify using 1099 earnings — built for contractors, freelancers, and gig-economy professionals paid outside a W-2.

Factory-Built

Manufactured Home Loans

Financing structured around manufactured homes, on owned or leased land.

Mobile Home

Mobile Home Loans

Financing for mobile homes — a program we've been arranging more frequently for our Utah and Idaho clients.

Every situation is different — call, text, or email to review your numbers and see whether one of these programs fits.

On Rates

Rates move by the hour.

Mortgage rates shift throughout the day and vary by credit, down payment, property and program — so a number posted here would be stale before you read it. Please call, text, or email if you have questions on rates for any loan program, and we'll walk you through where things stand right now.

The Process

Three unhurried conversations.

I.

Consultation

We listen first. We understand your goals — the move, the rate, the timeline — and we explain the lay of the land before any paperwork begins.

II.

Tailored Options

We present a small set of well-considered options, with the trade-offs spelled out plainly. You will know exactly what you are signing and why.

III.

Seamless Close

From application to keys, your file is handled by a single, accountable advisor. Most approvals are completed within 48 hours of documents.

Client Voices

Trust, earned one file at a time.

★★★★★

"Krest Mortgage has been amazing to work with. My family and I have worked with them on the purchase of our properties, and every experience has been excellent. They go above and beyond to make what can be a stressful process feel straightforward and smooth and are always responsive, clear, and genuinely invested in helping you succeed. I highly recommend Krest Mortgage to anyone looking for a team that's professional, trustworthy, and truly committed to their clients."

— Kerry Haymore
★★★★★

"We've had an excellent experience working with Krest Mortgage on our purchases. The team is knowledgeable, dependable, and consistently willing to take the extra steps needed to keep everything moving smoothly. Communication was clear, questions were answered promptly, and the entire mortgage process felt far less overwhelming. It's obvious they genuinely care about their clients and work hard to help each transaction succeed. I would confidently recommend Krest Mortgage to anyone looking for a trustworthy and supportive mortgage team."

— Miranda Haymore
An Invitation

Begin a confidential consultation.

A phone call, text, or email, on your schedule, with no pressure and no fee — in most cases we'll have a good idea of your options within twenty minutes. We'll outline them and tell you — candidly — whether now is the right moment to move.

The Principals

Reach us directly.

No call center. No queue. The two names below are who you'll speak with — and whose desk your file will sit on, start to finish.

Broker

Jeff H. Worthington

NMLS · 307846

Founder of Krest Mortgage, its principal broker, since 2004 — and a licensed Utah lender since 1996. Jeff has guided two generations of Utah and Idaho families to the closing table.

Senior Loan Processor

Shay L. Olsen

A trusted second voice on every Krest file. Shay shepherds first-time buyers, VA borrowers, and refinances with a meticulous, calm hand.

Frequently Asked

Straight answers, plainly put.

What loan programs does Krest Mortgage offer?

Conventional, FHA, VA, USDA, and refinance loans — including rate & term, cash-out, and FHA/VA streamline refinances — plus specialty programs for borrowers who don't fit the traditional route, including bank statement, profit & loss statement, asset depletion, and 1099 loans, along with manufactured and mobile home financing. Each is explained plainly, across the desk, during your consultation.

Does Krest Mortgage finance manufactured or mobile homes?

Yes — it's a program we've been arranging more often for our Utah and Idaho clients. Call, text, or email to talk through what a manufactured or mobile home purchase or refinance would look like for you.

When does PMI fall off a conventional loan?

Private mortgage insurance falls off once your loan reaches 80% loan-to-value.

Can I roll closing costs into a refinance?

In most cases, yes — on a rate-and-term refinance, closing costs can typically be rolled into the new loan amount. Before you commit, we'll review the numbers with you to confirm it makes financial sense and go over the breakeven point.

Why doesn't Krest Mortgage post rates online?

Rates move throughout the day and vary by credit, down payment, property and program, so a number posted online would be inaccurate almost immediately — and displaying a rate requires an APR disclosure alongside it. Call, text, or email us for an accurate, personal quote.

What states does Krest Mortgage lend in?

We're licensed to lend in Utah, where Jeff has been a licensed lender since 1996, and in Idaho since 2024.

How long does a consultation take, and what does it cost?

About twenty minutes, by phone, text, or email — with no pressure and no fee. In most cases that's enough time to give you a clear picture of your options.

Where is Krest Mortgage located?

20 N. Main Street, Suite 311, St. George, UT 84770. We're licensed to serve clients throughout Utah and Idaho.